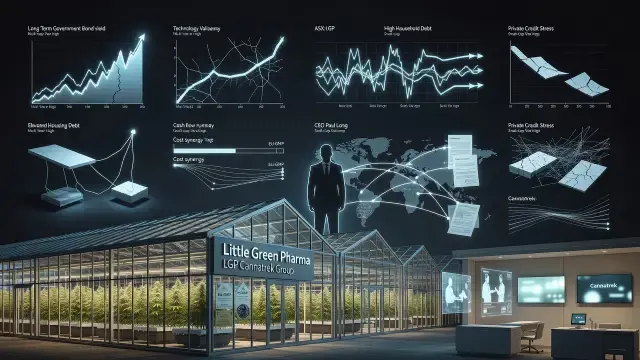
A prudential regulator's note about bond yields and tech valuations might seem far removed from a Danish greenhouse or an Australian cannabis clinic. It isn't. For Little Green Pharma, now trading as the LGP Cannatrek Group (ASX:LGP), APRA's latest System Risk Outlook is a reminder that small, capital-hungry companies live or die by conditions set well above their own balance sheets.
What APRA Actually Said
The Australian Prudential Regulation Authority flagged that long-term government bond yields in advanced economies are sitting near multi-year highs, with elevated government debt and persistent uncertainty behind the move. Markets remain orderly for now, APRA said, but a sharp further rise in yields - or a reassessment of stretched technology valuations, or stress in private credit - could trigger a more disorderly adjustment. Locally, the regulator pointed to softer housing prices and slower lending, warning that high household debt could amplify any downturn if falling prices collided with a jump in unemployment.
None of that is specific to cannabis. But it is specific to small, loss-making or pre-profit companies that depend on capital markets to fund operations. When yields rise and risk appetite falls, speculative stocks are usually the first repriced, and the smallest names tend to feel it hardest.
Where LGP Cannatrek Sits
Little Green Pharma completed its merger with Cannatrek earlier this year via a scheme of arrangement, creating a combined group in which former Cannatrek shareholders hold the majority stake. Paul Long remains chief executive. The result is a business with cultivation in Denmark, EU-GMP and AU-GMP manufacturing, clinics, a digital health platform, and distribution reaching Germany, France and the UK - a genuinely cross-border operation for a company that still trades at a low absolute share price on the ASX.
That low share price cuts both ways. It can mean outsized percentage swings on relatively modest shifts in sentiment, which is exactly the kind of volatility that shows up when the broader market pauses after a run, as the ASX 200 did following its recent five-session rally. Healthcare and REITs held up better than miners and retailers in that session, but elevated bond yields still weighed on the tone across small caps generally.
The Real Test: Cash Flow, Not Headlines
Mergers in the cannabis sector are rarely about growth for growth's sake anymore. The industry has shifted from a land-grab mentality to one where investors reward companies that can show a credible path to positive cash flow without constantly returning to the market for fresh capital. LGP Cannatrek's pitch is scale: combining LGP's Danish cultivation base with Cannatrek's Australian market presence, targeting cost synergies across manufacturing and corporate overhead, and leaning on Cannatrek brands, which already contribute the larger share of group sales.
That's the plan on paper. In practice, integration is where mergers either prove their logic or quietly unravel - duplicated supply chains, overlapping compliance obligations across AU-GMP and EU-GMP regimes, and the operational grind of aligning two distribution networks into one. The group reported a solid cash position at the end of June, which buys some runway. Whether that runway is long enough depends on execution speed and on European demand materializing as hoped, given that regulation, pricing and competition differ sharply from one export market to the next.
Funding Conditions Will Decide the Pace
For a company this size, the practical implication of APRA's warning is straightforward: if yields stay elevated, raising capital gets more expensive, and investors grow less patient with businesses still proving out their cost synergies. That doesn't make LGP Cannatrek's strategy wrong. It does mean the margin for error is thinner than it would be in a calmer funding environment.
- Integration progress across cultivation, manufacturing and distribution will be watched closely by investors
- Delivery of targeted cost synergies is the clearest near-term proof point
- European export demand remains promising but uneven across Germany, France and the UK
- Broader funding conditions, tied to bond yields and risk appetite, will shape how easily the group can raise capital if needed
Until the merged group demonstrates sustained cash generation rather than projected synergies, the shares are likely to stay sensitive to shifts in risk appetite well beyond its own control - a fairly ordinary position for a small-cap, but one worth stating plainly rather than glossing over.